Global coffee chains, including Starbucks and Costa Coffee, have rolled out ube ranges, tapping into trending flavours and social media buzz. Ube, a Southeast Asian root vegetable also known as a purple yam, has recently drawn global attention for its vivid purple colour and distinctive taste. The ingredient has gone viral online on social media, accelerating its rise as the “next matcha”. This is substantiated by a Q1 2026 survey1, in which over 60 % of Gen Z and millennials stated that they use social media to discover products in new flavours, and over half say that when they find a new flavour they like, they enjoy sharing it on social media, says GlobalData, a leading intelligence and productivity platform.
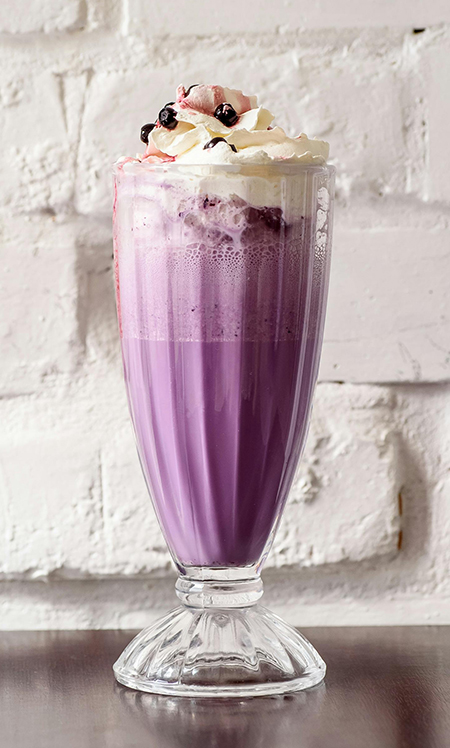
Ube is an “Instagrammable” ingredient (Photo: pexels-kirowang-7463309)
Brands are responding by building shareability into product launches. Starbucks, for example, introduced its Ube Vanilla Velvet Latte, Ube Vanilla Velvet Matcha, and Ube Vanilla Macchiato – promoted with multiple TikTok posts (via Starbucks and Starbucks UK) featuring pour shots and seasonal lines such as “spring is purple this year” and “ube vanilla, a new way to sip this spring.” This social-first playbook helps Starbucks reach younger consumers where they discover, evaluate, and recommend new drinks.
Jessica Butler, Consumer Analyst at GlobalData, comments: “Ube’s bold hue is instantly recognisable in feeds, and its highly “Instagrammable” look lends itself to sharing, especially in trendy café settings. It is an “Instagrammable” ingredient in every sense – high-impact visuals, easy to recognise, and made to be shared. That matters because social platforms are now a primary route to discovery for younger consumers. Brands should treat a launch as a content strategy as much as a product release – building in scroll-stopping visuals, creator partnerships, and easy-to-share moments that turn trial into amplification.”
Curiosity is powering trial
Ube also taps into younger consumers’ appetite for novelty. Many Western consumers haven’t tried it before, which makes it feel new – and worth a test. In Q1 2026 survey, 64 % of Gen Z and 65 % of millennials said curiosity motivates them to try new flavours. With trends moving fast – iced coffee, then matcha, now ube – brands can win by innovating at pace. Costa Coffee is doing this by adding ube to familiar formats on its UK spring menu, including a Sweet Ube Hot Chocolate and Sweet Ube Frappe, making the trend feel approachable.
Wellness cues add extra pull
Ube’s “better-for-you” halo is another tailwind. It contains vitamins, minerals, and antioxidants, and has been linked to benefits such as supporting blood pressure and blood sugar. As health-led decision-making rises, this matters: 68 % of Gen Z and 70 % of millennials say health and wellbeing always or often influence their choices. That gives brands permission to position ube as natural and plant-based – while keeping claims credible and compliant.
Innovative at-home formats a powerful opportunity for brands
Ube is beginning to transfer into retail. UK superfood-infused beverage brand Revibed recently launched ube powders in Holland & Barrett, positioned for smoothies, lattes, and baking, and marketed as a “simple, versatile single ingredient format.” That points to a wider opportunity for powders, syrups, concentrates, and RTDs.
Butler concludes: “The next step is turning ube from a viral café moment into an everyday staple. Brands should build social-first launches, introduce ube in ‘safe’, familiar formats, and expand into at-home and functional options – while getting sourcing and authenticity right.”
1GlobalData 2026 Q1 global consumer survey was conducted with 21,000 respondents across 42 countries
Rising consumer demand for convenient, high-protein, and multifunctional beverages is reshaping the global coffee market, with the proffee trend, coffee blended with protein, emerging as one of the fastest-growing developments in functional drinks. The shift is supported by a 2025 Q4 consumer survey1, which found that 66 % of global respondents stated that their food and drink purchases are always or often influenced by a product’s impact on health and wellbeing, while 61 % said that time and budget considerations shape their choices, according to GlobalData, a leading intelligence and productivity platform.
Originally popularised through social media and fitness communities, proffee has rapidly evolved from a niche lifestyle habit into a commercially significant category. Health-conscious consumers and fitness enthusiasts are increasingly adopting protein coffee as a practical way to boost daily protein intake while maintaining coffee’s familiar taste and energising benefits.
Nishitha Ranga, Consumer Analyst at GlobalData, comments: “Consumers are redefining coffee’s role in their daily routines, moving beyond caffeine toward beverages that support broader wellness and performance goals. The proffee trend reflects a growing preference for ‘all-in-one’ drinks that deliver energy, nutrition, and convenience, particularly among younger, health-conscious consumers balancing fast-paced schedules with fitness and wellbeing priorities.”
The rise of proffee reflects a broader convergence between traditional beverage categories and sports nutrition. Coffee is increasingly being used as a functional delivery system for protein, vitamins, and other performance-oriented ingredients, mirroring the wider shift toward hybrid beverages that combine multiple health benefits in a single product.
This convergence is being driven by the growing popularity of high-protein diets, the expansion of the fitness economy, and consumer interest in products aligned with weight management, muscle recovery, and sustained energy.
Ranga adds: “Convenience is emerging as a key driver of the proffee trend. With busy lifestyles, beverages that combine caffeine and protein are increasingly used as breakfast replacements, mid-morning snacks, or post-workout recovery drinks. Proffee aligns perfectly with the needs of time-pressed consumers, offering portable, nutritionally balanced, and satisfying options.”
Social media and fitness culture accelerate adoption
Social media platforms and fitness communities have played a critical role in scaling proffee, with influencers promoting it as a convenient post-workout or on-the-go breakfast solution. Viral recipes and lifestyle content have helped normalize adding protein to coffee, expanding the trend’s appeal beyond athletes to office workers, students, and busy professionals seeking sustained energy and improved satiety.
Brands respond with new launches across cafés and retail
The growing popularity of proffee has prompted coffee operators and functional beverage brands to introduce protein-enhanced offerings across both café and ready-to-drink formats.
In September 2025, Starbucks introduced protein-enhanced lattes and cold foam options across stores in the US and Canada, allowing customers to customise beverages with 15–36 g of protein. In the same month, Bulletproof introduced High Protein Iced Coffee, an instant iced coffee mix designed for busy, health-focused consumers, offering 12 g protein per serving from premium whey protein and formulated with no artificial flavours or sweeteners.
In August 2025, Tim Hortons launched hot and iced protein lattes made with a lactose-free, high-protein dairy base, delivering up to 20 g of protein per serving. Beyond major chains, challenger brands have also entered the space. In July 2025, Javy Coffee launched a protein-fortified coffee concentrate aimed at digital-first consumers seeking convenient, clean-label nutrition, delivering 10 g protein per serving.
These launches highlight how the proffee trend is being shaped by both global operators and niche wellness-focused innovators, signalling strong cross-category momentum.
Ranga concludes: “The proffee trend illustrates how consumer expectations around beverages are evolving from single-purpose refreshment to multifunctional nutrition. Brands that successfully balance taste, texture, and credible protein delivery will be best placed to capitalise on this shift. As the functional beverage market continues to diversify, proffee is likely to remain a key driver of innovation within the global coffee industry.”
1GlobalData 2025 Q4 global consumer survey was conducted with 22,613 respondents across 42 countries.
2018 was a banner year for social commerce with the public listing of major players in the industry. In fact, social commerce has indeed assumed a crucial role in digital retailing as latest research from Mintel reveals that a whopping 87 % of urban Chinese consumers* have bought, sold or shared information on products or services through social commerce platforms.
Currently, preference for shopping via social commerce channels equals that of traditional ecommerce platforms (39 % vs 41 % respectively). Mintel research indicates an even more optimistic outlook for social commerce in the days ahead – as 45 % of Chinese consumers would like to use social commerce platforms more in the future, as compared to the 32 % who say the same of traditional ecommerce channels. In addition, over half (51 %) of China’s post-90s generation intend to use social commerce platforms more in the future; while just under a third (31 %) intend to shop on traditional ecommerce platforms.
Cici Wu, Research Analyst, Mintel China reports, said:
“Social commerce is playing a crucial role in the digital retailing industry, especially with the public listing of major players in the market in recent months. Essentially everyone in China is jumping on the social commerce bandwagon and showing great enthusiasm for the platforms by engaging in a variety of social commerce activities. Although more consumers today still prefer traditional ecommerce than social commerce channels, their expectations for the latter are more optimistic. Our research shows that consumers who are the future of China’s economy, specifically the post-90s generation, favour social commerce over traditional ecommerce platforms.”
Seizing the ‘He’ economy
Men appear particularly engaged in social commerce, a growing trend that brands in the space could play into. Indeed, Mintel research reveals that over half (52 %) of consumers who engage in selling activities on social media platforms are male, compared with 48 % of females.
Men demonstrate stronger purchase power in the categories of personal electronics (eg smartphones, gaming devices) (41 % male vs 25 % female), household appliances (eg rice cooker, vacuum machines) (34 % vs 28 %), health supplements (30 % vs 28 %) and virtual services (eg online course, financial services) (21 % vs 18 %).
Further showcasing the potential in tapping into the ‘He’ economy, Mintel research reveals that a sizable proportion of men are purchasing in categories that are traditionally female-led in terms of consumption; as many as three in five (61 %) male consumers purchase clothing, shoes and accessories from social commerce platforms, as compared to 68 % of female consumers. Meanwhile, 46 % of male consumers purchase household cleaning products, in comparison to 48 % of female consumers. When it comes to beauty items, over a third (35 %) of male consumers say that they buy beauty and personal care products, while 62 % of females say the same.
“Making profits from the pockets of women and kids is a business practice that many have left behind in recent years. A more free and fluid market has helped unlock the spending potential and consumption desires of male consumers. Men’s shopping carts are no longer filled with just electronics, sports or game gadgets, but also include beauty products, groceries and cleaning products—categories that have been traditionally consumed by women. To tap into the ‘He’ economy, brands need to understand the change in men’s consumption habits for further growth. They also need to show an unbiased attitude towards this change and, at the same time, bear in mind their concerns and desires as individuals as well as other roles they assume like a father or husband.” Cici continued.
Fashion and beauty embrace social commerce
According to Mintel research, clothing, shoes and accessories is the most consumed category via social commerce platforms with two-thirds (64 %) of social commerce consumers having purchased these products in the past year*. This is followed by beauty and personal care products (48 %), food and drink products (48 %), and household cleaning products (47 %).
“As two of the most dynamic categories in the social commerce world, the development of the fashion and beauty industries are being driven by fashion and beauty influencers, or KOLs (key opinion leaders). Some of these KOLs have teams who produce high quality content as well as facilitate collaborations between the KOL and the brand. However, as it is becoming expensive to collaborate with top-tier influencers, micro influencers who engage in social commerce activities to communicate with like-minded people may be the way to go.
“Collaborating with micro influencers could open up more possibilities for fashion and beauty brands to increase brand awareness and preference, particularly as their interests go beyond financial returns, and instead, are driven by their own passion. That said, rather than solely revolving around the use of KOLs, marketing strategies that are theme driven or carried out in coordination with other marketing approaches, will work to a brand’s advantage in the long run.” Cici concluded.
*3,000 internet users aged 20-49, October 2018
You need to load content from reCAPTCHA to submit the form. Please note that doing so will share data with third-party providers.
You are currently viewing a placeholder content from Turnstile. To access the actual content, click the button below. Please note that doing so will share data with third-party providers.