The citrus belt in São Paulo recorded strong winds and above-average rainfall in July, raising concerns among market players, as these conditions may cause losses in orchards, reduce fruit quality (Brix), and delay the harvest. This is an atypical scenario for July, which is usually characterized by dry weather in the region. On the other hand, greater water availability may favour floral induction and the development of the next crop.
However, the full extent of the impacts has yet to be assessed. These adverse weather conditions may further worsen the production outlook, which has already been affected by citrus greening (HLB), a disease that causes premature fruit drop.
Data from Inmet indicate that Araraquara (São Paulo state) recorded 86.6 mm of rainfall in July, compared to just 9.1 mm in the same month last year. In Casa Branca (SP), rainfall totaled 59.8 mm, against only 5.2 mm in July 2025.
Besides heavy rainfall, strong winds also affected central São Paulo State. In Taquaritinga (SP), for instance, the winds caused fruit (especially lemons) and leaves to fall from the trees.
US tariffs
Although orange juice remained exempt from additional tariffs imposed by the US government, orange essential oils became subject to a 12.5 % surcharge, raising concerns among exporters, as the US market is a key destination for these by-products. According to CitrusBR, the measure took effect on July 24.
According to the in-depth study published by Vyansa Intelligence, the Juice Market in the United States is projected to grow at a CAGR of around 1 % during 2026 – 2032. The market growth is primarily driven by sustained demand for natural and 100 % juice products, increasing health consciousness among consumers, and strong distribution through retail channels across the country.
United States juice market key takeaways
The United States Juice Market is estimated at around USD 24.97 billion in 2025 and is projected to reach approximately USD 26.78 billion by 2032, reflecting stable growth supported by consistent consumer demand and gradual product innovation.
By category, 100 % juice dominates the market with approximately 45 % share, driven by increasing consumer preference for natural, minimally processed beverages perceived as healthier alternatives to sugar-sweetened drinks.
By sales channel, the off-trade segment accounts for nearly 75 % of the market share, supported by strong presence of supermarkets, convenience stores, and growing online retail platforms.
More than 20 companies are actively engaged in the US juice market, indicating a competitive yet moderately consolidated landscape.
The top five companies collectively account for around 40 % of the market share, including Vita Coco Inc, Naked Juice Co, The Campbell’s Company, The Coca-Cola Company, and Tropicana Products Inc, among others.
Key factors driving the growth of juice market in the US
Rising demand for natural and 100 % juice products
The US juice market is primarily driven by a growing consumer shift toward beverages that offer perceived health and nutritional benefits. Increasing awareness of clean-label products, transparency in ingredient sourcing, and the avoidance of added sugars and artificial additives have significantly strengthened demand for 100 % juice. As a result, consumers are actively opting for products that are natural and minimally processed. In response to this evolving preference, manufacturers are expanding their portfolios with premium offerings, particularly not-from-concentrate juices, to align with the rising demand for quality and authenticity.
Strong retail distribution supporting off-trade sales
In addition to product preferences, the widespread availability of juice products across retail channels continues to play a crucial role in market growth. The dominance of off-trade channels, comprising supermarkets, hypermarkets, convenience stores, and online platforms, ensures high product accessibility and visibility. These channels offer a diverse range of options, competitive pricing, and convenient purchasing experiences, making them the primary point of sale for consumers. Furthermore, the rapid expansion of e-commerce and direct-to-consumer models is reinforcing retail-driven consumption, thereby strengthening the overall market landscape.
Product diversification and packaging innovation
Alongside distribution strength, continuous product innovation is further supporting market expansion. The US juice market is witnessing diversification across categories such as juice drinks, nectars, and fruit and vegetable blends, catering to a broader range of taste preferences and price segments. At the same time, companies are investing in advanced packaging solutions, including PET bottles, aseptic cartons, and portable on-the-go formats, to enhance convenience, extend shelf life, and improve product appeal. These innovations are enabling brands to remain competitive while addressing evolving consumer lifestyle needs.
Key challenge impacting the market growth
Mature market limiting high growth potential
Despite steady demand and ongoing innovation, the US juice market faces notable growth constraints due to its mature nature and high level of market penetration. Established consumption patterns limit opportunities for rapid expansion, while shifting consumer preferences toward low-sugar beverages, functional drinks, and alternatives such as flavoured water and plant-based beverages pose additional challenges. Moreover, increasing scrutiny regarding sugar content in beverages continues to impact traditional juice consumption. As a result, while the market remains stable, its overall growth trajectory is expected to be moderate in the coming years.
Transformative industry moves and functional innovation redefining the US juice landscape
The US juice market is witnessing a dynamic phase of transformation, driven by strategic investments, product innovation, and a growing focus on health-oriented beverages. In 2025, PepsiCo strengthened its position in the evolving beverage landscape by acquiring prebiotic soda brand Poppi for approximately USD 1.95 billion. This strategic move highlights a broader industry shift away from traditional high-sugar juice products toward functional, low-calorie, and gut-health-focused beverages, reflecting changing consumer preferences.
At the same time, legacy juice brands are re-entering the market with refreshed offerings. Odwalla, backed by Grupo Jumex, relaunched its portfolio in 2025 with a new range of smoothies and juices made from real fruit, free from added sugars and artificial ingredients. Packaged in glass bottles and Tetra Prisma cartons, these products are specifically designed to attract health-conscious consumers seeking clean-label and premium beverage options.
Further reinforcing this trend, Suja Organic expanded its product portfolio in 2024 by introducing ready-to-drink protein shakes. These beverages, formulated with plant-based protein sources such as pea, rice, and hemp, along with essential nutrients and functional ingredients like acacia fiber, mark the brand’s entry into the rapidly growing functional beverage segment. Collectively, these developments underscore a clear industry transition toward innovation, diversification, and alignment with evolving consumer health and wellness trends.
Market analysis by category and sales channel
By category, 100 % juice continues to lead the US juice market, accounting for approximately 45 % of the total share. This dominance is largely driven by its strong health perception, natural composition, and absence of added sugars or artificial ingredients, which align with evolving consumer preferences. Furthermore, its widespread availability across retail channels enhances accessibility and consumption. Within this segment, not-from-concentrate juices are gaining notable traction as consumers increasingly prioritise freshness, quality, and minimal processing. Meanwhile, juice drinks and nectars continue to appeal to price-sensitive consumers, offering affordable alternatives and a variety of flavours, thereby supporting overall market stability and sustained demand.
By sales channel, the off-trade segment dominates the US juice market, capturing approximately 75 % of the overall share. This leadership is primarily supported by the country’s extensive retail infrastructure, including supermarkets, hypermarkets, convenience stores, and rapidly expanding online platforms. These channels provide consumers with easy accessibility, diverse product offerings, and competitive pricing, making them the preferred point of purchase. Additionally, frequent promotions, discounts, and bulk purchasing options further enhance consumer engagement and drive repeat purchases. The continued growth of e-commerce and direct-to-consumer models is also strengthening retail sales, ensuring that off-trade remains the primary driver of juice consumption across the United States.
Major juice companies in the United States
Key companies contributing to competition and innovation in the market include:
In the first half of the 2025/26 financial year (the six months ended 31 August 2025), AGRANA, the food and industrial goods group, registered a reduction of 50.5 % in operating profit (EBIT) to € 28.0 million. The Group’s revenue decreased by 9.1 % to € 1,691.6 million (H1 previous year: € 1,861.7 million). Nevertheless, thanks to very good second-quarter results in the Food & Beverage Solutions business, AGRANA has raised its forecast for the year and now expects a significant increase in Group EBIT of between 10 % and 50 %. EBIT is now projected to be in the range of about € 45 to 60 million for the 2025/26 financial year; this takes into account that the outlook for the Agricultural Commodities & Specialities business (the Starch and Sugar segments) remains subdued.
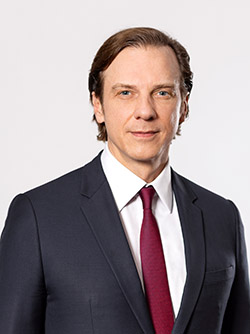
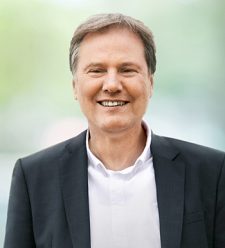
Stephan Büttner (Photo: AGRANA)
AGRANA Chief Executive Officer Stephan Büttner says: “We are still in a challenging transformation phase as we implement NEXT LEVEL, our new Group strategy. While the results in Food & Beverage Solutions were very positive, the operating performance in the Sugar and Starch businesses was unsatisfactory. Additionally, as announced, non-recurring expenses (primarily staff costs) were recognised in the Sugar segment as part of the restructuring in Austria and the Czech Republic. The strong earnings contribution from the Food & Beverage Solutions segment not only was a stabilising factor for Group EBIT in the first half of the year, but also forms the main basis for our updated EBIT forecast for the full year 2025|26.”
AGRANA Group financial results, first half of 2025/26 (1 March – 31 August 2025)
The Group’s net financial items amounted to an expense of € 19.7 million, compared to an expense of € 19.4 million in the year-earlier period. The slight increase was due primarily to a marked deterioration in currency translation differences that outweighed a significant improvement in net interest expense. After an income tax expense of € 7.1 million, corresponding to a tax rate of 85.5 % (H1 previous year: 36.8 %), profit for the period was € 1.1 million (H1 previous year: € 23.5 million). Net debt as of 31 August 2025 decreased by € 28.6 million from the 28 February 2025 year-end level, to € 407.8 million. The gearing ratio at the quarterly balance sheet date was a steady 35.5 % (28 February 2025: 35.5 %).
As a result of price changes, revenue of the FBS segment in the first half of 2025/26 was € 859.1 million, a moderate increase from the same period one year earlier.
EBIT of the FBS segment as a whole rose to € 68.0 million in the first six months of the financial year (H1 previous year: € 50.4 million), with sales volume remaining stable overall.
Food & Beverage Solutions (FBS)
As a result of price changes, revenue of the FBS segment in the first half of 2025/26 was
€ 859.1 million, a moderate increase from the same period one year earlier.
EBIT of the FBS segment as a whole rose to € 68.0 million in the first six months of the financial year (H1 previous year: € 50.4 million), with sales volume remaining stable overall.
Revenue of the “ACS – Sugar” segment in the first half of 2025|26, at € 309.6 million, represented a significant reduction from one year earlier. The main reasons for the decline were significantly lower sales to the reseller sector and lower sugar sales prices.
The EBIT result deteriorated sharply year-on-year to a deficit of € 36.3 million. Price pressure was relatively high in the deficit markets (Central & Eastern Europe region), which had a negative impact on sales volumes with resellers. In connection with the restructuring of the sugar business (the closure of the sugar production facilities in Leopoldsdorf, Austria, and Hrusovany, Czech Republic), expenses of € 20.0 million, mostly in the form of staff costs, were recognised in the first half of 2025/26. This exceptional item had an added negative impact on EBIT.
Outlook
At Group level for the full 2025/26 financial year, AGRANA expects a significant increase in operating profit (EBIT) compared with the previous year. Group revenue is projected to show a moderate decrease. The Group’s total investment this financial year, at approximately € 100 million, is expected to be both significantly below the 2024|25 value and significantly less than the budgeted depreciation of about € 113 million.
The Southeastern region in Brazil, especially citrus areas in São Paulo, Paraná and part of Minas Gerais, registered rains in the first week of spring. Although this scenario brings optimism, since it favours the upcoming blossoming, strong winds caused fruit droppage. Players surveyed by Cepea say that the region of Avaré (São Paulo) was one of the most affected areas.
The return of the rainfall is extremely important for the 2026/27 blossoming to be in the normal standard, which was not verified last year – after a warm and dry winter, rains returned more consistently after October, which delayed the current crop.
Symrise continued its profitable growth trajectory in the first nine months of the year, achieving organic sales growth of 11.1 %. Considering portfolio and exchange rate effects, Group revenue rose to EUR 3,824 million in the first nine months (9M 2023: EUR 3,610 million), a plus of 5.9 % compared to the year-ago period. Both segments contributed to the positive development and increased sales in a global economic environment that remained challenging. In the third quarter, overall sales increased organically by 10.2 %. Despite negative exchange rate effects of 4.0 %, sales grew by 5.2 % in the reporting currency. Against the backdrop of robust organic growth, Symrise has specified its organic growth target, sales expected to come in at around 7 %.
Jean-Yves Parisot, CEO of Symrise AG: “Symrise was able to seamlessly continue the positive business development of the past months in the third quarter. Despite the current volatile market environment due to geopolitical tensions and continued inflation pressure, we are confident for the rest of the year and expect robust demand. Our diversified portfolio and broad, international footprint will continue to help us realise our growth potential and create sustainable value this year. We are firmly convinced that we have set the right course for the future.”
Sales development by region
The strongest organic growth was recorded in the Latin America region with 27.4 %, followed by the Asia/Pacific region with 11.2 % and EAME (Europe, Africa, Middle East) with 11.1 %. The main growth drivers were the Food & Beverage, Fragrance, Aroma Molecules and Pet Food business units. The North America region achieved organic growth of 2.3 %, driven primarily by the Food & Beverage and Aroma Molecules business units.
High growth in food, beverages and pet food
The Taste, Nutrition & Health segment increased sales organically by 10.4 % in the first nine months of the current fiscal year. In the third quarter, organic growth was 11.3 %. Taking into account portfolio and currency effects, the segment’s revenue rose to EUR 2,349 million in the first nine months (9M 2023: EUR 2,267 million). The portfolio effect from the sale of the beverage trading business in the UK within the Food & Beverage business unit had a negative impact of EUR 27 million on sales development.
The Food & Beverage division achieved double-digit organic growth in percentage terms. Strong growth impulses came from the application areas for sweet and savory products and beverages. All four regions, especially the EAME region, achieved high growth. The Naturals application area increased its revenues, especially in the North America and EAME regions.
The Pet Food division also achieved double-digit organic growth in percentage terms in the first nine months. Sales development was particularly dynamic in the Asia/Pacific and Latin America regions, with double-digit organic growth.
Sales development in the Aqua Feed business unit recorded declining organic growth. As part of the further portfolio streamlining with a focus on high-margin growth areas, Symrise intends to sell the business.
The probiotics business, which includes the majority stake in the listed company Probi AB, Lund, Sweden, generated slight growth, driven by the EAME region.
Strong sales growth in Consumer Fragrance and significant recovery in Aroma Molecules
The Scent & Care segment, which manages the fragrances, perfumery applications and cosmetic active ingredients business, achieved organic sales growth of 12.2 % in the first nine months and 8.4 % in the third quarter respectively. Taking into account portfolio and currency effects, revenue for the first nine months amounted to EUR 1,475 million (9M 2023: EUR 1,343 million).
The Fragrance division increased its sales organically in the double-digit percentage range in the first nine months. In particular, the Consumer Fragrance application area achieved double-digit percentage growth. The EAME, Asia/Pacific and Latin America regions in particular experienced very high market dynamics. The Fine Perfumery application area also continued its very positive development and achieved high single-digit percentage organic growth. Here, the Latin America and Asia/Pacific regions recorded good growth. The Oral Care application area achieved single-digit percentage organic growth, with good growth especially in the North America and Asia/Pacific regions.
Sales in the Aroma Molecules division recovered significantly in the first nine months of the current year. While the market environment continues to prove challenging, the resumption of production in Colonels Island, USA has resulted in a significant year-on-year increase in revenue. High double-digit growth figures were achieved in all regions.
Sales in the Cosmetic Ingredients division continued to develop strongly with high single-digit percentage organic growth. Revenues increased significantly in the EAME, Asia/Pacific and Latin America regions. Only the North America region showed just a slight year-on-year growth. The application areas for micro-protection and actives and botanicals also recorded very strong growth impulses.
Symrise specifies growth target for 2024
Based on the good business performance in the first nine months, Symrise is specifying its sales target for the full year 2024. The Group is now aiming for organic sales growth of around 7 %. The Group’s long-term organic growth expectation of 5 % to 7 % (CAGR) remains unchanged. The long-term EBITDA margin is expected to be in the range of 20 % to 23 %.
Elopak rounded off a highly successful 2023 with yet another strong quarter, delivering on the mid-term targets set by the company during its IPO in 2021.
2023 was a year of significant progress and achievements for Elopak, extending the many successes of previous years in implementing the company’s sustainability driven growth strategy. The Board proposes a dividend of NOK 1.46 per share for the year 2023, in line with dividend policy.
Fourth quarter 2023 highlights
Revenues increased by 7.5 %, to EUR 287.2 million
Organic growth was 8.4 %, or EUR 22.4 million, adjusted for currency translation effects
Adjusted EBITDA was EUR 40.0 million, an improvement of EUR 4.1 million, reflecting a 13.9 % margin
Strong cash flow generation and down-payment of debt. Leverage ratio reduced to 1.9x
Commenting on Elopak’s performance, CEO Thomas Körmendi said: “I am happy to report yet another quarter of strong performance and I am pleased to confirm that the Elopak team has delivered on all the 3-5 year targets set in the IPO in 2021.”
“I would like to say a big thank you to all our colleagues, customers, suppliers and partners for their fantastic contributions and collaboration throughout the year. We are entering 2024 from a strong position and I look forward to further strengthening our contribution to a more sustainable society while continuing to create shareholder value in the years to come,” Körmendi added.
Full Year 2023 highlights
Revenues increased by 10.6 %, to EUR 1,132.0 million
Organic growth was 9.4 %, adjusted for currency translation and acquisition effects of EUR 11.9 million
Adjusted EBITDA was EUR 170.9 million, an improvement of EUR 51.5 million, reflecting a 15.1 % margin
Adjusted profit attributable to Elopak shareholders was EUR 68.3 million, up 55 % compared to 2022
Proposed dividend of NOK 1.46 per share for the year 2023, in line with the dividend policy
Elopak reported strong financial performance for the second quarter of 2023
Highlights:
Revenues increased by 8 %, to EUR 278.0 million, driven by growth in EMEA and Americas
Organic growth was 6 %, or EUR 14.6 million, adjusted for currency translation effects and revenue from acquired businesses
Adjusted EBITDA was EUR 41.6 million, an improvement of EUR 15.1 million
Strong cash flow generation, leverage ratio reduced to 2.6x
Elopak will build a new plant in the USA to further leverage the high customer demand in the region
Commenting on Elopak’s performance, CEO Thomas Körmendi said:
“Building on our solid performance in past consecutive quarters, Q2 saw Elopak delivering strong profitable growth. Despite inflationary pressures, we remain on-track to achieving our strategic objectives. Our strong performance is allowing us to explore new market opportunities, including building a new state-of-the art factory in the US, and expanding our India operations.“
“Looking forward, we expect to deliver full year revenue growth well above our mid-term target. While we see softening of some raw material prices, the liquid paper market remains tight and higher board prices will have full effect in the second half of 2023. Additionally, the significant inflationary pressures on the broader cost base will impact our full year EBITDA margin. However, based on expected revenue growth, our second half EBITDA will be higher than last year. I am pleased to report this strong performance and remain eager and optimistic for continued sustainable packaging demand.”
The climate impact of food is important to Europeans. Three out of five consumers consider climate impact when buying food according to a new survey by Yara.
Yara International announced the findings in a new European survey on sustainable food conducted by leading international market research company IPSOS on behalf of Yara. The report provides an overview of consumer purchasing habits and sustainable food preferences.
“The report shows that Europeans are highly motivated to buy sustainable food to reduce their climate impact. This should be a wake-up call to the entire food industry,” says Birgitte Holter, VP of Green Fertilisers at Yara. “While three out of five Europeans find the climate impact important when buying food, a majority feel it is not easy enough to understand available information about the climate emission to be able to make sustainable choices. More than three out of four consumers would prefer to be able to read the carbon footprint on the food item,” Holter says.
The world’s food production accounts for more than a quarter of global greenhouse gas emissions. This new report shows that 58 % of Europeans consider the climate impact important when buying food and beverages. In addition, 51 % of Europeans are willing to pay more for fossil free food items, meaning food produced without fossil sources. However, most people feel that it is not easy to know which food is climate friendly, as 76 % of Europeans would like the carbon footprint to be visible on the food label.
“Decarbonisation of food is possible and that is why we are developing green fertilisers made from water and air using renewable energy, to support farmers and food companies in reducing their climate impact of their food. These voluntary choices must be supported by adequate policies. The EU’s Sustainable Food System initiative, planned for the end of 2023, should therefore create a set of incentives for food systems’ actors to go beyond the minimum requirements and favor low-carbon footprint solutions such as green fertilisers,” says Holter.
In Porsgrunn, Norway, Yara is building the first production plant to run on renewable energy. From here, Yara will produce green fertilisers made without the use of fossil energy or fossil sources. This will result in crops with an up to 30 % lower carbon footprint and up to 20 % carbon footprint reduction in the food produced, making them a powerful solution to grow a decarbonised and fossil free food future. The first green fertilisers are planned to enter production in the second half of 2023.
The market demand for food made without fossil energy sources is high. More than half of Europeans (51 %) said they are willing to pay more for climate friendly food. A clear majority of Europeans (74 %) say food companies need to work to reduce the emissions from their food production.
Key findings in this survey:
58 % of Europeans consider the climate impact important when buying food and beverage items
69 % of Europeans would choose a climate friendlier food item versus a cheaper option. (26 % would choose a fossil free food item, 43 % would choose a low-carbon item)
51 % of Europeans say they are willing to pay more for food made without fossil fuel sources
31 % of Europeans already make sustainable choices when it comes to their buying habits
More than three out of four (76 %) Europeans want to see the carbon footprint of food items on the label
Nearly three out of four Europeans (74 %) believe food companies should work to reduce emissions in their food production
About the survey The survey on the need for sustainable food was commissioned by Yara International and conducted by IPSOS. The panel consisted of 12,000 consumer respondents in France, Germany, the United Kingdom, Ireland, Italy, Spain, Poland, Romania, Turkey, Norway, Sweden and Denmark (1,000 respondents in each country). The data was collected from online interviews during the period of December 1 – 14, 2022.
Elopak reported revenue growth of 7 % in Q2 supported by price increases and successful onboarding of Naturepak. This was achieved despite the discontinued operations in Russia.
Highlights from Q2 2022:
Revenue increased by 7 %, to EUR 259 million, driven by growth in EMEA and Americas
New revenue from acquired businesses in MENA and India was EUR 12 million in the quarter
Continued high raw material prices impacted the Q2 results negatively by approximately EUR 14 million
Adjusted EBITDA was EUR 25.3 million, reflecting an adjusted EBITDA margin of 9.8 %
The leverage ratio increased to 3.4x as of second quarter 2022, primarily driven by dividend payment in May and lower Last Twelve Months EBITDA compared to last year
Elopak completed the acquisition of GLS Elopak to supply Roll Fed and Pure-Pak® cartons to the Indian market
Commenting on Elopak’s performance in the quarter, CEO Thomas Körmendi said:
“I am pleased to announce strong revenue growth and profitability for Elopak in the second quarter. We are actively mitigating the unprecedented raw material prices and the challenging business environment. We expect margins to improve in the second half of 2022.
At Elopak, we are committed to delivering on our sustainability-driven growth strategy. We are very excited about entering India in a partnership with leading Indian packaging provider GLS, positioning Elopak in one of the world’s biggest and fast-growing markets. Further, the second quarter saw the post-merger integration and full first quarter of Naturepak operations as part of the Elopak Group. We continue to implement different value enhancing initiatives across all markets, aimed at improving both our top- and bottom-line.
I also want to praise our colleagues in Ukraine for their impressive resilience, managing to ramp up production despite all the challenges. Our Russian operation was sold to the local management this summer, following our earlier announcement that we were suspending our operations in the country in Q1.”
As of 30 June 2022, Year to date revenue increased by 8 %, to EUR 502.5 million. Year to date adjusted EBITDA was EUR 52.3 million, reflecting a 10.4 % margin.
Louis Dreyfus Company B.V. (LDC) reported strong consolidated financial results for the year ended December 31, 2021, successfully fulfilling its key role to keep essential agricultural supply chains moving safely, reliably and responsibly in a context of continued global challenges.
Net sales amounted to USD 49.6 billion, up 47.7 % compared to 2020, while Segment Operating Results rose 17.6 % year-on-year to USD 1,834 million, as the company once again leveraged its global footprint and market intelligence to mitigate risk, deliver for customers and capture profitable origination and sales opportunities. This performance drove EBITDA to USD 1,623 million, up 22.6 % compared to the same period in 2020.
“2021 was a very special year for LDC, in which we celebrated 170 years of history and opened a new chapter for the company, welcoming ADQ into our shareholder group as a strategic partner in the pursuit of our long-term plans and strategy,” said Margarita Louis-Dreyfus, Chairperson of the Supervisory Board. “It was also another challenging year for our teams and partners around the world, to whom I am deeply grateful for their exceptional commitment, which made business continuity and success possible even in a complex and rapidly changing context.”
With overall resilient demand for the main products commercialized by the Group in 2021, both its business segments contributed to LDC’s strong operating results, which reached USD 1,191 million for the Value Chain Segment (compared to USD 1,003 million in 2020) and USD 643 million for the Merchandizing Segment (up from USD 556 million in the previous year). All business platforms successfully navigated uncertain market conditions, securing profitable flows to meet demand, implementing successful hedging strategies and capitalizing on recovery from Covid-19 impacts in certain sectors, owing to easing sanitary measures.
“In another year marked by the ongoing pandemic, freight shortages and port congestions, as well as climate challenges, LDC once again navigated a complex environment to deliver for customers, while making important strides in our strategic and sustainability roadmaps,” said Michael Gelchie, LDC’s Chief Executive Officer. “Our clear vision and agile mindset have underpinned our success over 170 years, and continue to do so today as we pursue our growth ambitions, always with the safety and wellbeing of all those who work for and with us as a top priority.”
As part of its commitment to helping address increasingly urgent climate and other global sustainability challenges, LDC set up a dedicated Carbon Solutions Platform in 2021 to accelerate the Group’s decarbonization journey. This reflects the sectoral commitment, signed at the COP26 United Nations Climate Change Conference, for accelerated action on deforestation and emissions, supporting the global drive toward a net zero economy.
“Our progress in 2021 further reinforced LDC’s leading position as a key industry participant for the future, while ensuring the future we shape is fair and sustainable, in line with our company purpose,” said Michael Gelchie. “Looking ahead, in light of new geopolitical tensions and macroeconomic shifts emerging in 2022, our role to provide essential products to the world’s population is more important than ever. It remains our priority to fulfill this role safely, reliably and responsibly, working hand in hand with our teams and business partners across the globe, to whom we are extremely grateful for their collaboration and steadfast support.”
Please download the full LDC’s digital 2021 annual report as pdf-file under: www.ldc.com
Symrise AG outstandingly capitalized on the economic recovery in 2021 and successfully continued the profitable growth course. The Group once again significantly increased sales and earnings. Symrise grew Group sales in reporting currency by 8.7 % to € 3,826 million (2020: € 3,520 million). Without taking into account portfolio and currency effects, organic growth amounted to 9.6 %. Earnings before interest, taxes, depreciation and amortization (EBITDA) at € 814 million were significantly above the prior-year figure of € 742 million. The Group maintained profitability at a high level with an EBITDA margin of 21.3 % (2020: 21.1 %). Against the backdrop of the positive development, the Executive Board and the Supervisory Board of Symrise AG propose a dividend increase for the 12th year in succession. Shareholders are to participate in the success of the company with a dividend of € 1.02 for the fiscal year 2021.
Dr. Heinz Jürgen Bertram (Photo: Symrise)
“2021 was a successful year all round for Symrise. We made good use of the tailwind generated by the global economic recovery and we aligned our sails accordingly. As a consequence, we very successfully continued our course of profitable growth. Additionally, we were also able to realize trailblazing purchases and investments. This allowed us to strategically diversify our know-how and our portfolio, further increase our appeal to customers and differentiate our profile in the market. Since September, Symrise has also been a member of the DAX, Germany’s leading index. As a result, our share has continued to gain a higher profile and enhanced appeal, particularly on the international capital markets. Part of our capital market philosophy is for our shareholders to participate in the successful development of Symrise AG. The Executive Board and Supervisory Board therefore propose the twelfth dividend increase in succession in the amount of € 1.02 for the year 2021,” said Dr. Heinz Jürgen Bertram, CEO of Symrise AG. “For the current fiscal year, we confirm our long-term target to achieve an average increase in sales of between 5 and 7 % (CAGR) and to exceed market growth. Furthermore, we are once again targeting high profitability for 2022 with an EBITDA margin of around 21 %, in spite of the increasing raw materials costs and energy prices.”
Economic recovery drives demand and leads to strong sales growth
The impacts of the coronavirus pandemic significantly diminished in large parts of the world over the course of the year. The behavior of consumers normalized and demand surged. Symrise increased sales in reporting currency by 8.7 % to € 3,826 million (2020: € 3,520 million). Organic sales growth amounted to 9.6 %. Symrise not only exceeded the average growth of the relevant market but also the most recent sales forecast issued in November 2021 of around 9 %. Regarding the regions, Latin America once again recorded the strongest organic growth of 13.5 %, followed by Asia/Pacific with 10.3 %. The regions EAME and North America also delivered very good growth with 8.8 % and 8.5 % respectively.
Significant increase in EBITDA and net income
In fiscal year 2021, Symrise increased earnings before interest, taxes, depreciation and amortization (EBITDA) to an outstanding € 814 million. The Company exceeded the prior-year level by 9.6 % (2020: € 742 million) in spite of the increased raw materials costs and costs of strategic growth initiatives amounting to € 174 million.
The group-wide EBITDA margin rose in the second year of the pandemic to 21.3 % and therefore exceeded the prior-year level (2020: 21.1 %).
Symrise increased net income by € 68 million to € 375 million (2020: € 307 million). Earnings per share rose to € 2.74 (2020: € 2.27). In view of this positive development, the Executive Board and the Supervisory Board will propose to the annual general meeting on 3 May 2022 a dividend increase to € 1.02 per share for the fiscal year 2021 (2020: € 0.97).
Net debt with 2.4 in targeted margin range
As of 31 December 2021, net debt including pension and leasing liabilities decreased to € 1,964 million (2020: € 2,029 million). This corresponds to a ratio of net debt to EBITDA of 2.4.
The business free cash flow amounted to € 486 million (2020: € 564 million).In spite of the increase in earnings, it was defined above all by higher investments, an increase in inventories (strategic stockpiling in order to mitigate the risks due to delays in international supply chains) and a high level of trade receivables as a consequence of the strong growth in sales.
In a year-on-year comparison, the equity ratio rose from 39.8 % to 49.0 %. Symrise thus has a very solid foundation for continued sustainable growth of its business in the future.
Taste, Nutrition & Health segment
In April 2021, Symrise merged the former two segments Flavor and Nutrition into a new segment and renamed it Taste, Nutrition & Health to reflect the purposefully implemented portfolio expansion. It is intended to align the expanded activities even more closely with customer needs and hence make know-how, technologies and product knowledge a shared asset. Over the course of the year, Symrise strengthened the activities through the acquisition of the Canadian manufacturer Giraffe Foods and invested in a stake of the Swedish animal health company Swedencare. The core business no longer includes the food color application areas which have been sold to Oterra as well as the Drinkstar Velcorin activities. The distribution model with Lanxess was terminated effective 1 January 2022.
Taste, Nutrition & Health increased sales by 8.5 % to € 2,335 million (2020: € 2,151 million). Organic growth even amounted to 10.6 %. The change in behavior in out-of-home leisure activities and the increasing trend of on-the-go consumption resulted in a particular high demand for beverage applications. Furthermore, the segment benefited from very dynamic growth rates in the Pet Food segment.
Taste, Nutrition & Health increased EBITDA to € 531 million (2020: € 471 million). The EBITDA margin at 22.7 % was at an outstanding level and significantly exceeded the prior-year value (2020: 21.9 %).
Symrise confirms long-term growth and profitability targets
According to experts estimates, the global economy will slow down slightly in the current fiscal year after the strong recovery in 2021. Symrise is excellently positioned with its robust business model, the diversified application portfolio and its broadly based regional presence and customer base. The Company therefore confirms its long-term growth and profitability goals. Symrise continues to target above market growth and increase average annual sales by 5 to 7 % (CAGR). This objective also applies to the current financial year 2022, in spite of increasing raw material costs.
Symrise is committed to organic and inorganic growth, which includes the acquisition of the Dutch company Schaffelaarbos in January 2022 and the Chinese Wing Pet Food in February 2022. Furthermore, Symrise will maintain strict cost consciousness and continue the holistic sustainability management in all its divisions.
Profitability is projected to remain at a high level in 2022 with an EBITDA margin of around 21 %. Over the medium term until the end of fiscal year 2025, Symrise has a target of achieving an EBITDA margin in the corridor of 20 to 23 %.
You need to load content from reCAPTCHA to submit the form. Please note that doing so will share data with third-party providers.
You are currently viewing a placeholder content from Turnstile. To access the actual content, click the button below. Please note that doing so will share data with third-party providers.